MIFCO reverses canned tuna price hike hours after implementation

Apr 7, 2026, 10:03 AM
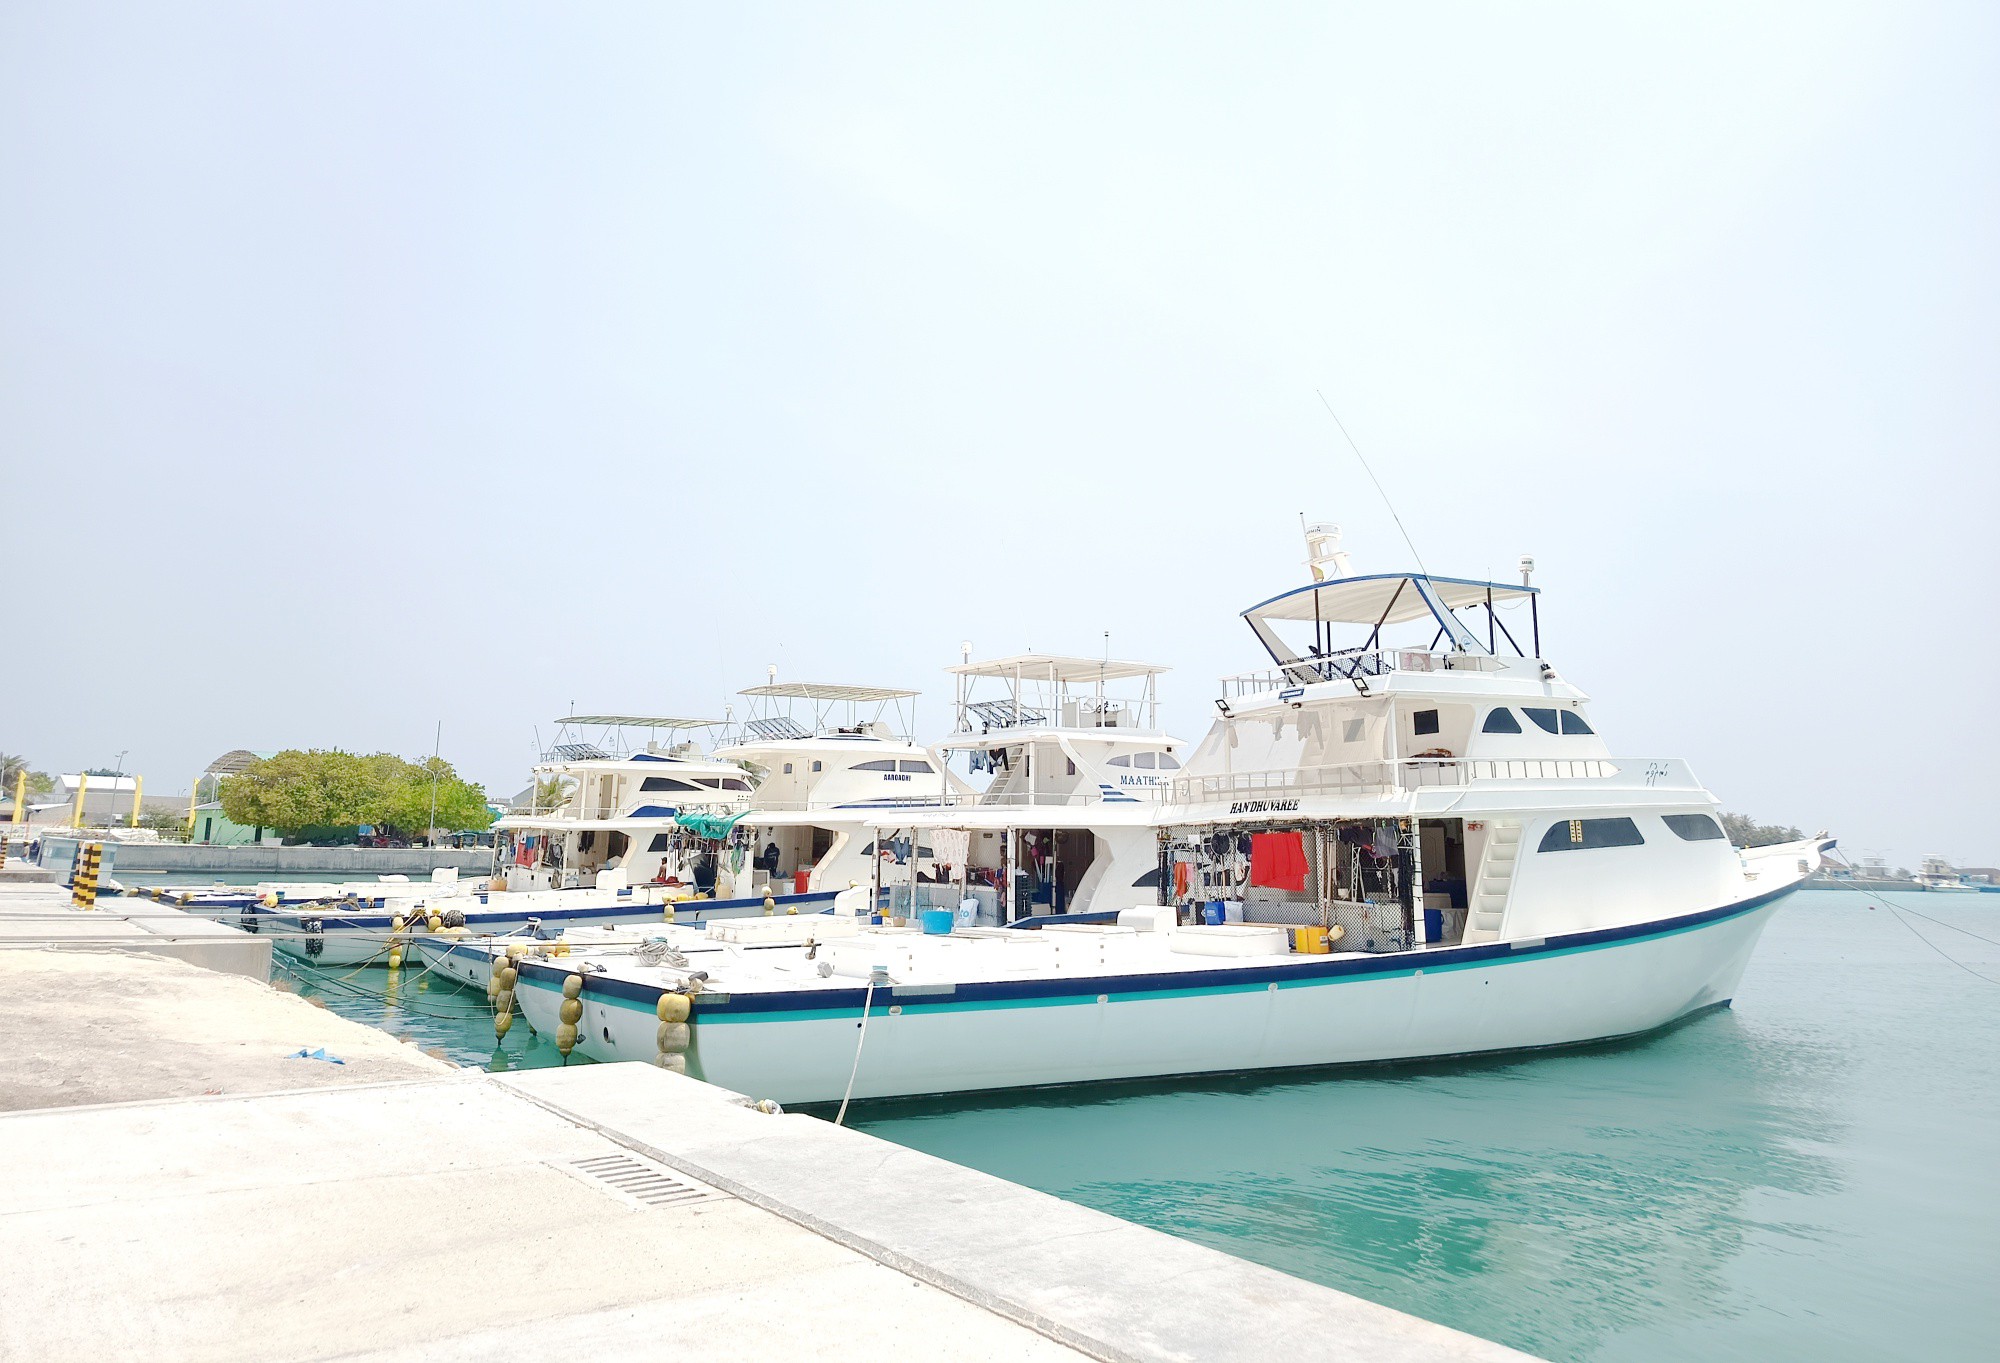
Felivaru Fisheries Complex.

Felivaru Fisheries Complex.

The Maldives Industrial Fisheries Company (MIFCO) has lowered the price of tuna cans at sunset on Monday after hiking prices at noon.

The price of canned tuna was increased citing changes in oil prices, less than two days after the elections, despite the government's assurance that no cost-cutting measures would be taken after the vote.

MIFCO raises tuna can prices after elections despite government assurance

MIFCO has increased the price of canned tuna due to rising global oil costs, despite prior government assurances that no such measures would follow the elections. To further manage operational expenses and the impact of regional conflict, the state-owned company has also shortened its administrative office hours.

MIFCO said they decided to reverse the price change after considering the people's opinion and the cost of living. 

MIFCO increased the price of canned tuna in oil to MVR 18.50. But the price has now been lowered back to MVR 17.50.

MIFCO said the price was increased due to the change in oil prices in the world market, which raised the production cost for tuna cans. 

The state-owned fisheries company noted that the price of a litre of oil has increased from MVR 11.57 to MVR 14. 32.

Meanwhile, MIFCO has shortened its office hours and is considering further measures to cut costs due to the Iran war.

MIFCO said the company's head office and administrative offices will be open from 8:00 am to 2:00 pm from today (April 6). Previously, offices were open until 4:00 pm.

The Maldives Industrial Fisheries Company is one of the oldest state-owned companies, but it continues to face many operational problems and relies on government subsidies due to losses. 

Comments

Read More

Latest News

Star Medical to host free pre-pregnancy session for couples

Star Medical will host a free pre-pregnancy awareness session for couples on September 24 at 8:45 pm. Led by experienced nurses, the event offers guidance on healthy conception and a Q&A segment. Interested couples can register by contacting the clinic directly.

Businesses face challenges in securing dollar support from BML

Bank of Maldives has notified businesses that dollar support for transfers is now strictly subject to availability. Importers face automatic cancellations if accounts lack full invoice amounts, as the bank struggles with a severe foreign exchange shortage. Business owners report receiving zero support and no prior notice of these changes.

Dollar transfers will return to normal within next week: BML

Bank of Maldives expects dollar transfer services to return to normal next week following recent delays caused by a surge in demand. The bank implemented measures to manage unsustainable outflows from Rufiyaa accounts, noting that the issue is a temporary supply imbalance and not a reflection of its overall financial health.

BML denies funding $50 million debt repayment to SBI

Bank of Maldives denied claims that it provided $50 million to the government for debt repayment to the State Bank of India. The bank clarified that no customer deposits or internal resources were used for the payment. BML maintained its financial stability despite ongoing dollar liquidity challenges and warned against spreading misinformation.

Exclusive: Maldives sought extension on $50M India debt

The Maldives government requested a further extension to repay a final $50 million debt installment to India, but the request was denied. Despite the refusal, the Maldives settled the payment last week using its Sovereign Development Fund. This follows previous rollovers and a $50 million grant provided by India earlier this year.

Businesses allege BML is blocking USD transfers

Business owners are accusing the Bank of Maldives of blocking USD transfers to other banks amid a liquidity crisis. Despite having sufficient funds, traders report significant delays in processing payments and transfers via the MRTGS system. BML cited a backlog, reportedly prioritizing essential imports like food and medicine.

Government settles final $50 million debt to SBI

The government has fully repaid a $150 million debt to the State Bank of India, settling the final $50 million installment this month. The debt, originally incurred in 2019, was cleared in three stages under the current administration. This payment is part of a broader $2.3 billion effort to service foreign debt over the last two years.

Newsletter

Get the latest news delivered straight to your inbox