BML denies funding $50 million debt repayment to SBI

Sep 19, 2026, 9:57 PM
BML CEO Shareef

BML CEO Shareef

Bank of Maldives (BML) today denied allegations that it provided the $50 million required by the Maldivian government to settle Treasury bills sold to the State Bank of India (SBI).

BML issued the clarification following claims by opposition figures suggesting that the bank’s current dollar liquidity challenges are linked to providing funds to the government for this debt repayment. The government had previously refuted these claims, stating that the payment was made using funds accumulated in the Sovereign Development Fund (SDF).

In a statement addressing the allegations, BML asserted that there is no connection between the government’s debt settlement and the bank’s financial position or banking operations.

"BML has not utilized any customer deposits or any of the bank’s own resources to facilitate this payment," the statement read.

While maintaining that the government’s debt repayment is unrelated to its financial standing, BML emphasized that the institution remains financially robust. The bank further noted that it operates within defined risk appetites, regulatory standards, and a stringent framework of governance and risk management.

BML stated that the government's transaction had no impact on the bank’s financial resources. The statement further assured customers that there are no obstacles to the bank fulfilling its obligations toward them.

Following these remarks, BML urged media outlets and political figures to verify information before commenting on the bank’s financial status. The bank added that it reserves the right to take legal action against those spreading misinformation intended to defame or damage the institution.

Despite BML’s assurances regarding its financial health, the bank continues to face significant dollar liquidity constraints, causing difficulties for individuals and businesses in making foreign currency transfers and payments. 
Comments

Read More

Latest News

Exclusive: Maldives sought extension on $50M India debt

The Maldives government requested a further extension to repay a final $50 million debt installment to India, but the request was denied. Despite the refusal, the Maldives settled the payment last week using its Sovereign Development Fund. This follows previous rollovers and a $50 million grant provided by India earlier this year.

Businesses allege BML is blocking USD transfers

Business owners are accusing the Bank of Maldives of blocking USD transfers to other banks amid a liquidity crisis. Despite having sufficient funds, traders report significant delays in processing payments and transfers via the MRTGS system. BML cited a backlog, reportedly prioritizing essential imports like food and medicine.

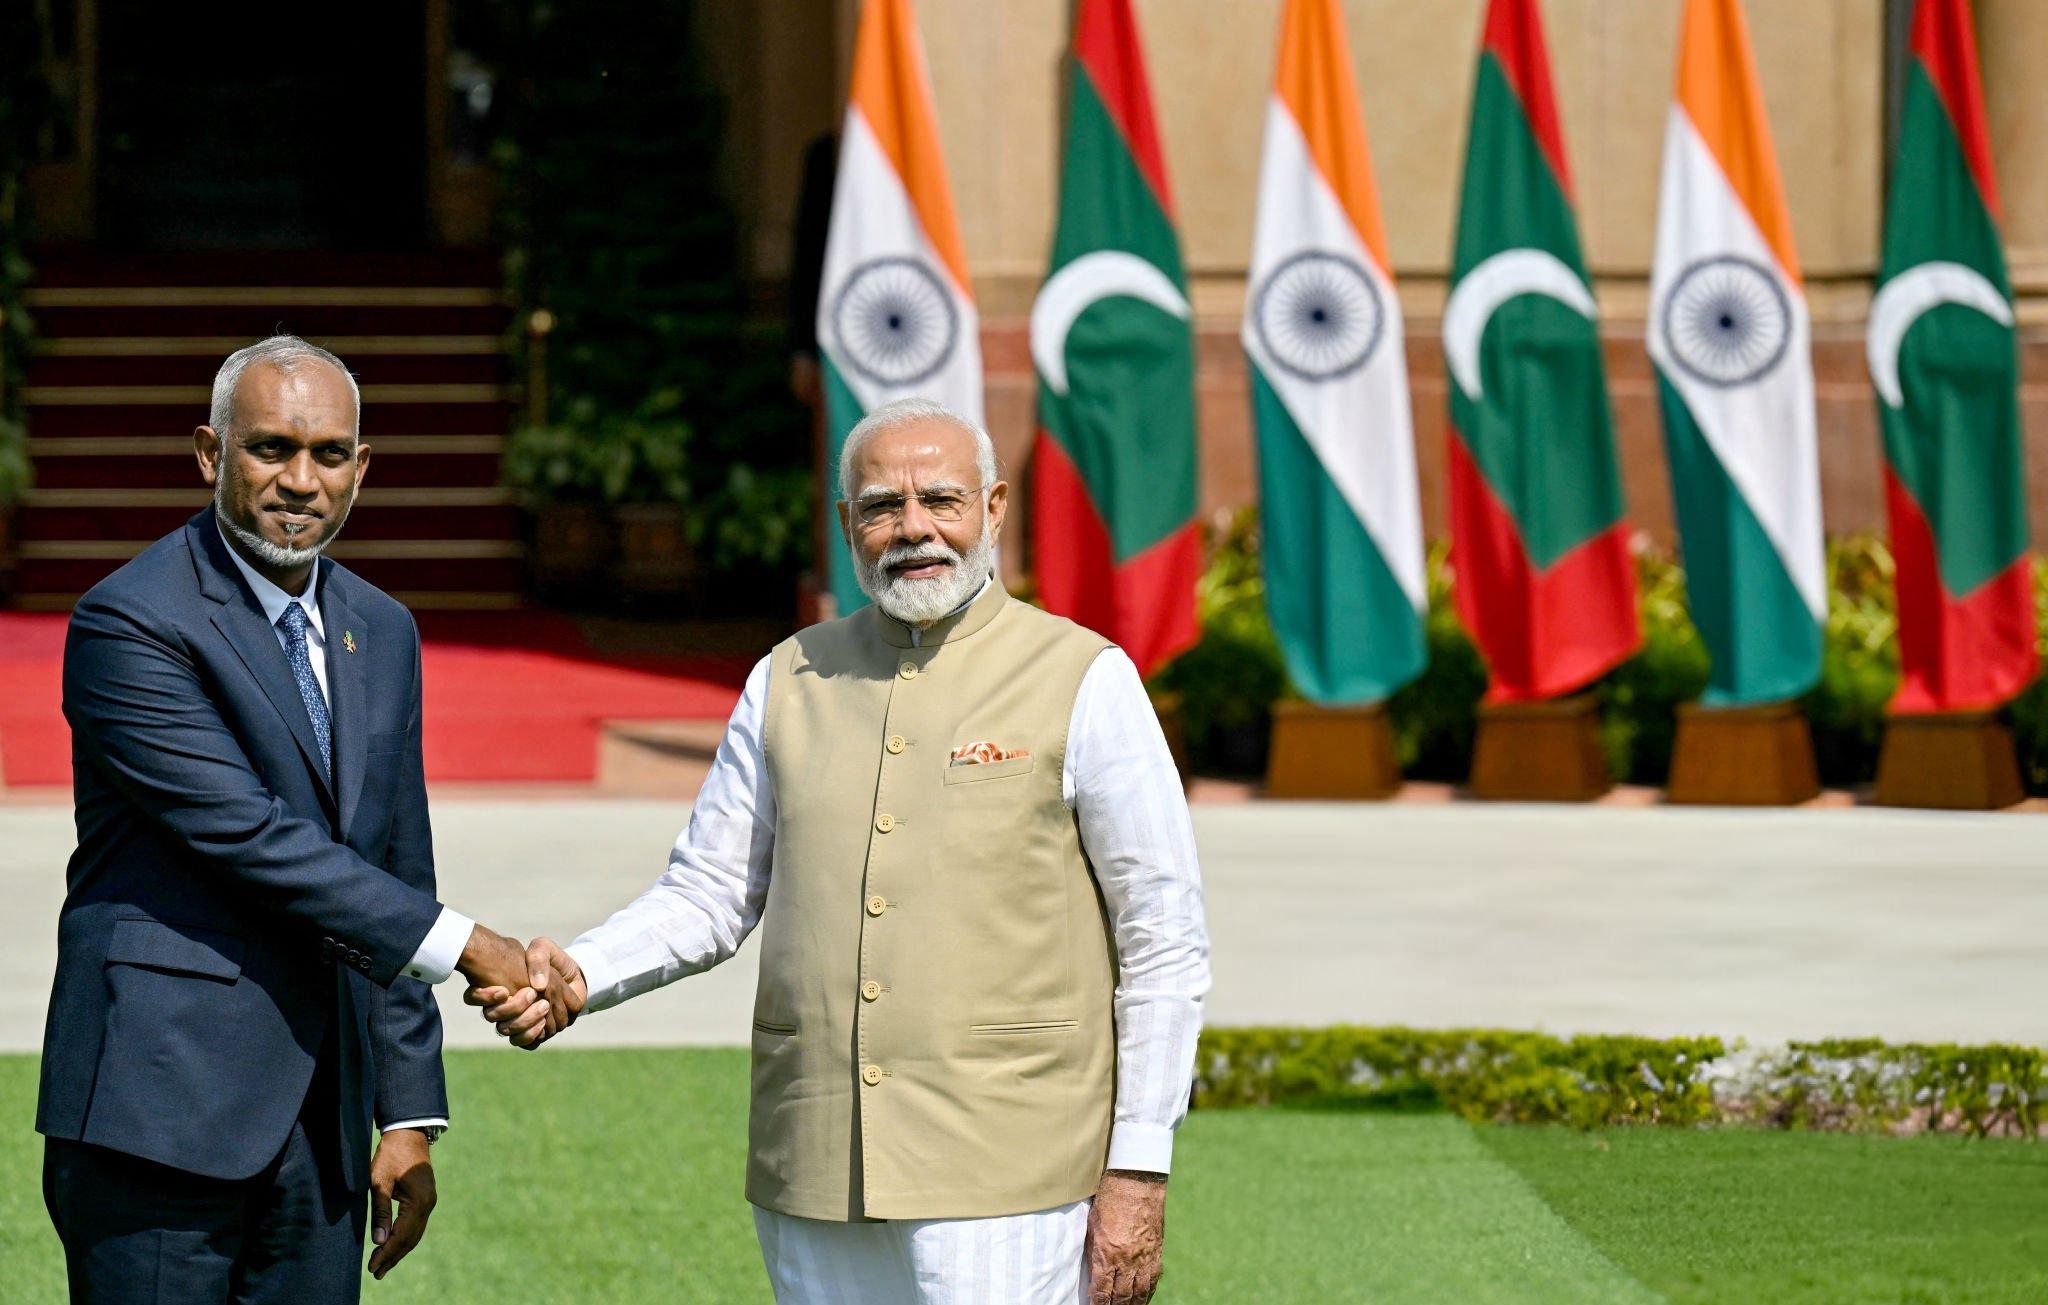
Government settles final $50 million debt to SBI

The government has fully repaid a $150 million debt to the State Bank of India, settling the final $50 million installment this month. The debt, originally incurred in 2019, was cleared in three stages under the current administration. This payment is part of a broader $2.3 billion effort to service foreign debt over the last two years.

Govt urged to suspend dollar mandate and tax changes

Tourism advocacy group Destination Future is urging the government to suspend a planned 40% foreign currency conversion mandate and new tax changes for tour operators. The group warns these measures could cause irreparable damage to the industry, which is already struggling with declining occupancy and rising supply costs.

Agents threaten Maldives boycott over proposed "double taxation"

Foreign tour operators are threatening to boycott the Maldives over a proposed 17% tax on their profit margins. Agents argue the "destination principle" policy leads to double taxation, as they already pay taxes in their home countries. Many warn they will shift focus to rival destinations if the government proceeds with the new regulations.

Insufficient funds for essentials after repaying $50 million loan

Former President Mohamed Nasheed warned that repaying a $50 million bond to India will deplete the Maldives' usable reserves. He cautioned that this financial strain will leave the government unable to afford essential imports like food, fuel, and medicine. The payment marks the final installment of a $150 million debt to the State Bank of India.

European tour operators are expressing concerns: Nasheed

Former President Mohamed Nasheed warned that a new mandate requiring resorts to convert 40% of foreign earnings into local currency could lead to bankruptcy. European investors and tour operators fear the policy leaves insufficient funds for dividends and debt. Nasheed urged the government to reconsider to avoid damaging investor confidence.

Newsletter

Get the latest news delivered straight to your inbox