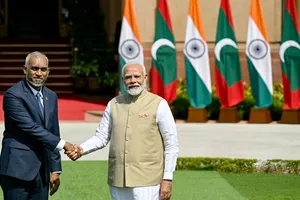
Indian media outlets have reported that legal and regulatory constraints may hinder the Maldivian government’s request to extend the USD 400 million currency swap facility with the Reserve Bank of India (RBI) for a third time.
The facility, initially secured through the Indian government in October 2024, was previously rolled over in April and October of last year. However, the specific terms and conditions of the SAARC Currency Swap Framework have made it difficult to reach a decision on the current proposal.
According to the Economic Times, the request faces challenges due to mandatory "cooling-off periods" required between drawdowns and established limits on the number of times a facility can be rolled over.
When questioned on the matter, both President Mohamed Muizzu and Finance Minister Moosa Zameer confirmed that a request for a rollover has been submitted.
Neither official, however, addressed the regulatory hurdles facing the Indian government. Instead, Muizzu and Zameer emphasised the close bilateral ties between the two nations and highlighted India’s history of providing generous assistance to the Maldives as a key partner.
If the USD 400 million swap facility is not rolled over and repayment becomes due, it will significantly increase the nation's debt obligations and place immense pressure on foreign currency reserves. This comes at a critical time, as reserves were already utilised earlier this month to facilitate Sukuk payments.
The government stated that the USD 500 million Sukuk principal and the USD 24.6 million coupon payment were settled using funds from the national reserves and the Sovereign Development Fund (SDF).
Prior to these substantial expenditures, usable reserves stood at USD 411 million at the end of last month. However, since the government has not disclosed the specific details of how these payments were structured, the current remaining balances in the reserves and the SDF remain unclear.
Given the current economic climate, a failure to extend the swap facility could have severe adverse effects on the economy. The primary risk is a further tightening of the dollar supply—a shock the country is ill-equipped to handle, as tourism faces a downturn due to regional conflicts and global oil prices continue to rise.